France plans to spend an extra €4 billion on school renovations by 2030 and a further €1 billion on universities by 2029, all while public debt stands at around 120% of gross domestic product. The report describes this as promising money the state does not have, and the arithmetic supports that judgment. A government that cannot balance its books should not be adding new spending commitments on top of an already heavy load.
The warning signs are concrete. France pays nearly 1.6 percentage points more than Germany on 10-year bonds, the widest spread since the financial crisis, and several rating agencies have assigned it a negative outlook. The report projects that France's interest bill will exceed €79 billion in 2026 and could reach between €125 billion and €132 billion by 2030. Every euro spent on debt service is a euro not spent on classrooms, universities or anything else the new plans promise.
The political debate has not caught up with these numbers. The report notes that the far-right National Rally wants to restore the retirement age of 62 while promising €140 billion in savings, and that La France insoumise's Jean-Luc Melenchon has suggested that bonds held by the French central bank should be "thrown into the fire." Friedrich Heinemann of the ZEW describes such proposals as economic fairy tales that promise a way out without consolidation or painful cuts. That verdict is fair, and voters deserve parties that acknowledge the trade-offs.
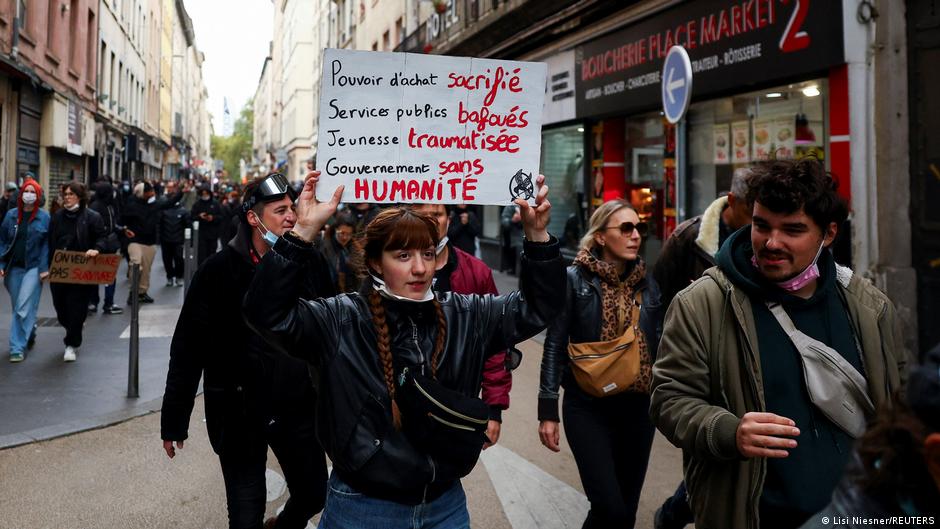
The harder question is why the pressure has not yet produced a change of course. The report cites research suggesting that 56% of the population receive more in benefits and services than they pay in taxes and contributions, which gives most people a tangible reason to resist adjustment. Because the euro has softened the signals that a currency devaluation once sent, the cost of borrowing has not yet felt like a crisis in ordinary life. That delay is precisely what makes the situation dangerous.
France should stop announcing new spending it cannot finance and instead set a credible path to reduce its deficit, with clear priorities for the investments that matter most. Schools and universities deserve funding, but funding that is paid for by ever-higher borrowing will eventually be paid for by everyone, through a financial crisis that would hit those same students and teachers hardest.